In select markets such as Mexico and Costa Rica, LOGAN offers appraisals for condominiums (condos). Usually, these are vacation homes – or second homes used for recreational purposes and are owned by foreigners from the United States, Canada, or Europe. There is sometimes a need for an appraisal that follows US standards – and written in English for use by US or international lenders.
Condos are in a multi-unit building but share ownership of common elements. Owners may modify the interior of their units, but the management of the condominium regime maintains the common areas.
Types
Construction
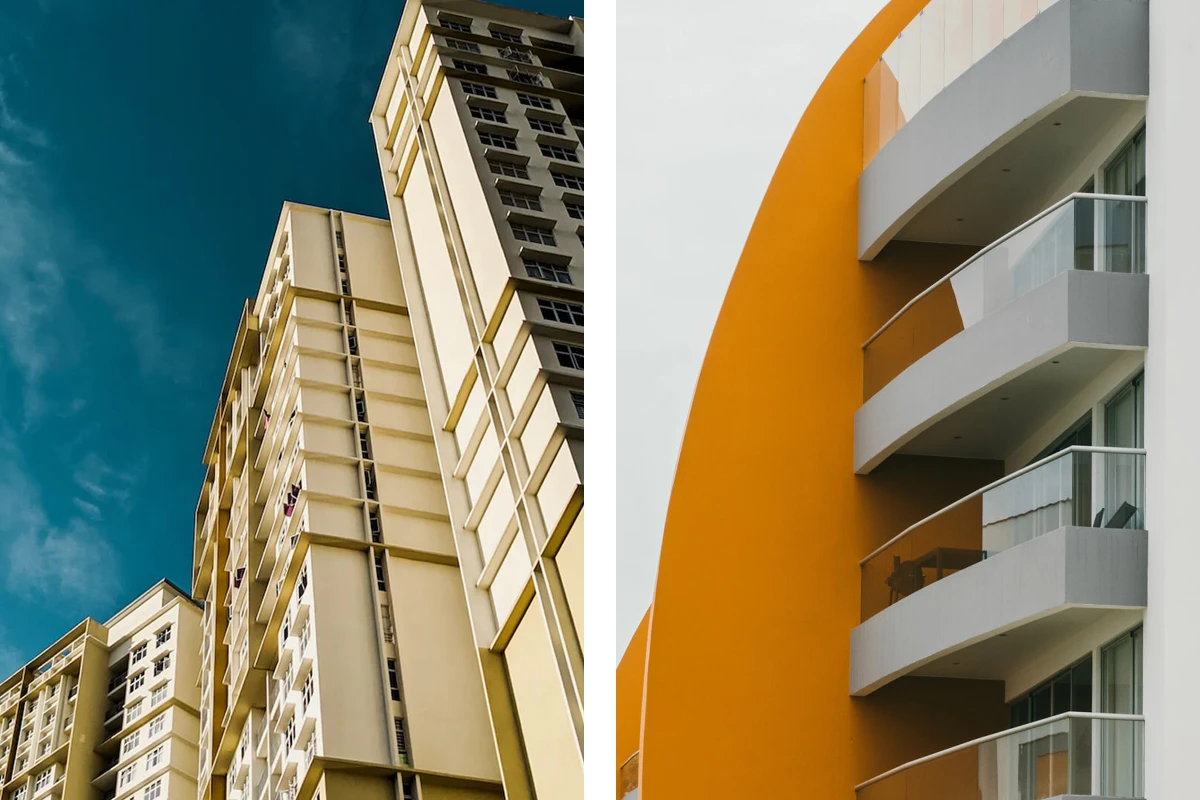
- High-rise
- Mid-rise
- Low-rise (Villa)
Ownership
Traditional – each condominium jointly owns the common property of the building or project. This often includes walkways, entrances, and amenities.
Condotel – condominium projects that have a front-desk and allow for short-term rentals and amenities for guests.
Resort Condominium – a building or cluster of buildings consisting of free-hold ownership, that have co-ownership interest in common elements which are shared with a resort. Units are rented with resort amenities for vacationers, who can enjoy the common elements of the resort.
Approaches, Relevance
Cost approach – due to special use and design of embassies and ambassador residences, the cost approach is more relevant.
Sales comp or market approach – sometimes difficult to find similar comparables – especially when the asset is a single-family home, as embassies usually own residences in in-fill locations where properties rarely trade. These ‘embassy zones’ usually have colonial or protected architectural homes, which do not trade very often. This approach is very common for condos and office properties.
Income capitalization – this approach may be applicable if there are similar embassy properties of other countries which are being rented. This approach can be used if the property is an office suite, building, or an income producing property.
DCF – could theoretically be applied, however, the property needs to have rent comparables available which are similar to the subject property. This approach is used when the property is an income producing property such as corporate office towers.
Residual – if an embassy property is a single-family home or stand-alone project without architectural restrictions for redevelopment, there cou
Cost – relevant when costs are known and can easily be depreciated. Newer projects may have the cost approach applied.
Sales comp or market approach – the most relevant approach when valuing condominiums, as there are often many similar comparable sales within the same project.
Income capitalization – may be relevant for condotel or resort condominiums, considering that there is a stabilized income.
DCF – can sometimes be applied if there is an income stream that can be evaluated. Such an income stream may come from
ld be hidden development potential in such property. Periodically, zoning laws change and allow for additional density to be developed, especially in infill locations. Sometimes, the highest and best use of these properties is re-development, whereas the land is valued, and the improvements do not contribute value.
Value Impacting Factors
Location – location impacts value significantly even within the same city. In some resort areas, being within a master planned community greatly impacts the value of condominium units. Being directly on a beach is often the most sought-after location in most resort areas, but that depends on the market.
Construction – high-end luxury apartments are designed differently than middle-market condos. This is indicated by ceiling height, the façade of the building, and the internal elements of the unit. High-end condominiums have top of the line appliances, flooring, and counter tops. Further, luxury condominium projects have extensive amenities which include pools, hot tubs, gyms, and sometimes restaurants.
Important Inputs
- Comparable sales that are within the same building or project
- Rental rate (condotel, and resort condominium)
- Management fee of the building
Recent Trends
Continued second home growth for foreigners (US, Canada, Europe) in markets in Mexico and Costa Rica specifically.
Pandemic and its effects on travel. Some markets have benefitted from the pandemic and others have suffered from less visitors.
Luxury condo resort projects that are now branded by some of the most luxurious brands in the world including, Ritz Carlton, Four Seasons and Rosewood.
Deliverable
Short Form Appraisal Report – Form 70
- Subject
- Contract
- Neighborhood
- Site
- Improvements
- Sales Comp Approach
- Cost Approach
- Income
- PUD/HOA Information
Notable Markets and Projects
| Colombia | Mexico | CR-CA |
|---|---|---|
| Cartagena – H2 | Los Cabos – Four Seasons Residences, Ritz Carlton Residences, The Enclaves, El Dorado, Las Ventanas | Papagayo – Four Seasons Residences |
| – | Riviera Maya – Mayakoba Residences | Tamarindo – Hacienda Pinilla |
| – | Puerto Vallarta – Four Seasons Residences | Mid-Pacific Coast – Los Sueños |
| – | – | – |
International Mortgage Brokers
| Colombia | Mexico | CR-CA |
|---|---|---|
| CMN Funding – Latam | Global Mortgage | Scotiabank |
| – | Mexlend | Desyfin |
| – | – | Gap Investments |
| – | – | Fast Costa Rica Finance |
International Title and Escrow Companies
| Colombia | Mexico | CR-CA |
|---|---|---|
| TLA Services – Latam | TLA Services | TLA Services |
| – | Secure Title | Secure Title |