Specialized Asset Types

Real Estate Fund Valuation

Overview

Value a real estate fund from an impartial viewpoint with a qualified team of professionals:

Opportunity

  • Increase the level of transparency
  • Implement systems to improve the efficiency of portfolio analysis and fund raising
  • Internal decision making, financial reporting, third party negotiations

Solution

Deliver a valuation report that follows the guidelines laid out by the IPA* and that adheres to international valuation standards:

  • Value the real estate fund every 2 years after the initial offering
  • Follow the ethical code of the Appraisal Institute, USPAP and International Valuation Standards
  • Report written by a member of the appraisal institute with the MAI designation or equivalent
  • Concluded value based on the individual asset values – utilizing discounted cash flow methods and Argus software


* Valuation of Publicly Registered, Non-Listed REITs.” Investment Program Association, 2013, ser. 01, 29 Apr. 2013. 01.

Deliverable

1. Valuation of the Assets that Comprise the Portfolio (Asset Approach)

Summary of the asset including the verification and modeling of the following variables:

Wholly Owned Assets

  • Discount Rates
  • Capitalization Rates
  • Growth Rates – Inflation
  • Market Rents

Partial Interests

  • Discount Rates
  • Income Participation Rates
  • Capitalization Rates
  • Growth Rates – Inflation
  • Market Rents
  • Equity Balances

Land

  • Comparable Sales, Comparable Rents (Comparable Method)
  • Residual or Discounted Cashflow (Income Method)

Discount Rates

  • Sensitivity Analysis
  • Discount Rates
  • Capitalization Rates (Entry)

2. Net Asset Value of the Assets (NAV, Net Asset Value)

Financial Analysis of the Entity

  • Short-term Debt
  • Medium and Long-term Debt
  • Minority Interests

Preferred Return, Special Interests, Return Incentives

  • Performance-based return adjustments (Waterfall)

3. Price per Share

  • Entity Control Analysis – Partnerships
  • Marketability Analysis

Leadership Team

Leadership Across Latin America's
Principal Markets.

Other case studies

CCLA – Multifamily Market Study Colombia

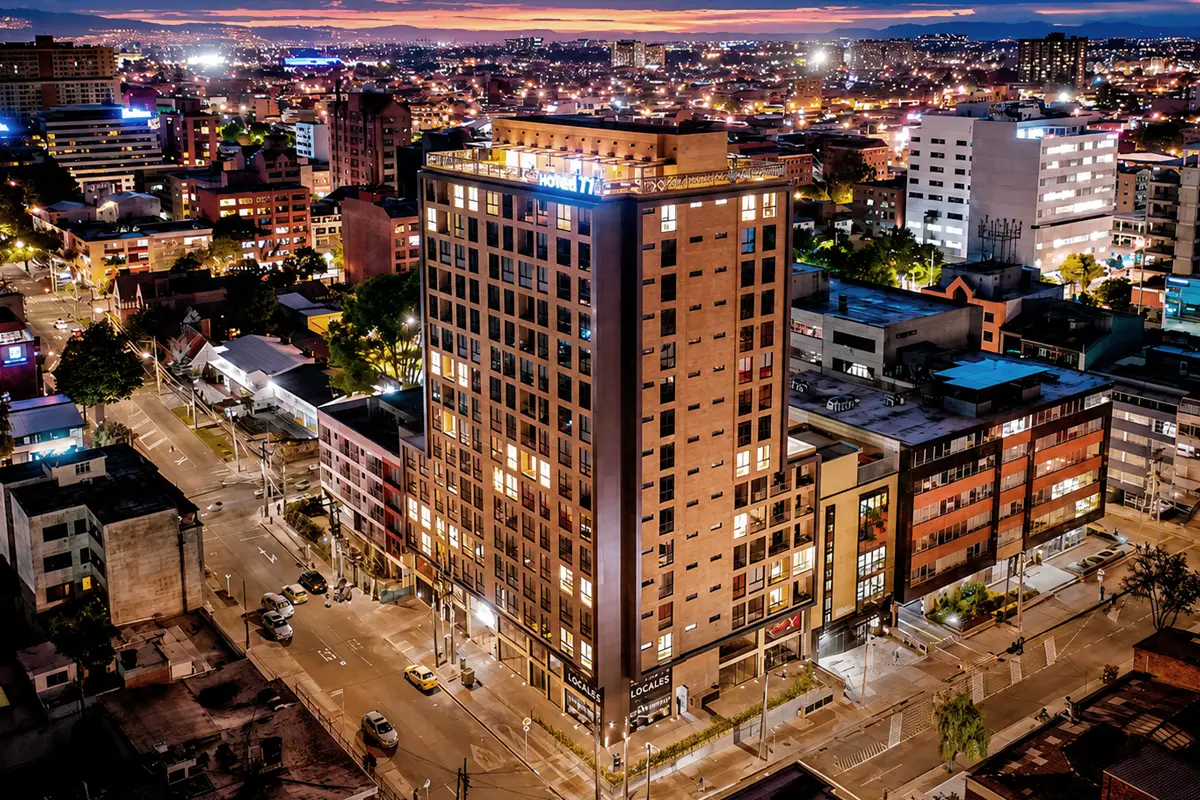
Project Leaders: Diego Rodriguez Rueda, MRICS; Paola Raba. Market analysis for the first institutional Multifamily project in Colombia, Nomad 77 (127 Units).

Latam Logistic Properties – Industrial Market Study Colombia, Peru

Project Leaders: Diego Rodríguez Rueda MRICS, Paola Raba Need The client needed to understand and keep track of the dynamics of the logistics.

Local teams. Regional standards.
One point of contact.

81st Street # 11-55, Ochenta 81 Building, North Tower, 6th Floor, Office 601, Bogotá, Colombia

Email: adminCO@loganvaluation.com
Phone: +57 (601) 467-4717
Hours: M - F 8.00 am - 5.30 pm

217 Mayor Armando Blondet Street, Office 901, San Isidro, Lima, Peru

Email: adminPE@loganvaluation.com
Phone: +51 (1) 702-7126
Hours: M - F 8.00 am - 5.30 pm

San Rafael de Escazu, District 4 North Coast – Amara CC, Office 408, 10203, Costa Rica

Email: AdminCA@loganvaluation.com
Phone: +506 4010-0565
Hours: M - F 8.00 am - 5.30 pm

Plaza Villa de Madrid No. 1, 10th Floor – Office “C,” Roma Norte, Cuauhtémoc, ZIP Code 06700, Mexico City, Mexico

Email: adminMX@loganvaluation.com
Phone: +52 (55) 9303-5017
Hours: M - F 8.00 am - 5.30 pm

86 Rafael Augusto Sánchez Street, Roble Corporate Center, 7th Floor, Office 10148, Santo Domingo, Dominican Republic

Email: adminCB@loganvaluation.com
Phone: +1 (849) 936-3683
Hours: M - F 9:00 am - 6:30 pm

Av. El Golf 40, 12th Floor, Las Condes, Santiago, 7550107

Email: AdminCH@loganvaluation.com
Phone: +56 (2) 2485-1345
Hours: M - F 8.00 am - 5.30 pm

Calle A-1, Urb. El Parque. Delta Tower, 6th Floor, Office No. 6-E, Barquisimeto, Lara State, Venezuela

Email: AdminVE@loganvaluation.com
Phone: +58 0424-5344823
Hours: M - F 8.00 am - 5.30 pm

Diagonal 6, 10-50, Zone 10, Interamericas Building, North Tower, Office 1601, Guatemala City, Guatemala

Email: adminCA@loganvaluation.com
Phone: +502 2294 4393
Hours: M - F 8.00 am - 5.30 pm